Estate & Date-of-Death Appraisals · DFW Metro

The value as of the date that matters.

Independent date-of-death and estate appraisals for executors, trustees, estate attorneys, and CPAs. Retrospective value documented for IRS filings, step-up in basis, probate, and settlement among heirs. Serving estates across Collin, Dallas, Denton, Tarrant, Rockwall, Ellis, and Grayson counties.

Retrospective effective dates · USPAP-compliant · Certified Residential, Texas

Assignments & effective dates

Sec. 01 · Scope
Date of death

Value as of the date of passing

A retrospective appraisal with the effective date set to the date of death, supported by comparable sales and market conditions from that period. This is the figure that establishes the stepped-up cost basis for heirs and the value reported on the estate tax return when one is required.

Alternate valuation date

Six months after

When the estate's attorney or CPA elects the alternate valuation date, the appraisal is prepared as of that date instead. Both dates can be appraised in a single engagement when the estate needs to compare them.

Current value

Sale, buyout, or distribution

A current market value appraisal for pricing the home for sale, for one heir buying out the others, or for dividing the estate fairly when the property is distributed in kind.

Trusts & gifts

Funding, gifting, and reporting

Appraisals for transferring a residence into or out of a trust, for gifts of real property, and for the valuation support a CPA needs on the related return.

How engagement works

Sec. 02 · Process
Step 1

Scope the assignment

A short call to confirm the property, the effective date or dates, who the client is, and who will rely on the report. Fee quoted in writing before engagement.

Step 2

Inspection & records

Inspection scheduled with the family or the executor at a convenient time. When the home has already changed hands, the appraisal proceeds from prior records and exterior observation.

Step 3

Report delivery

A complete, USPAP-compliant appraisal report with supported adjustments and period market analysis, delivered as a PDF to the client and any named intended users.

Step 4

Follow-up support

Available to answer questions from the estate's attorney or CPA, and to explain the methodology if the value is ever questioned.
Built for the file

Sec. 03 · Standards
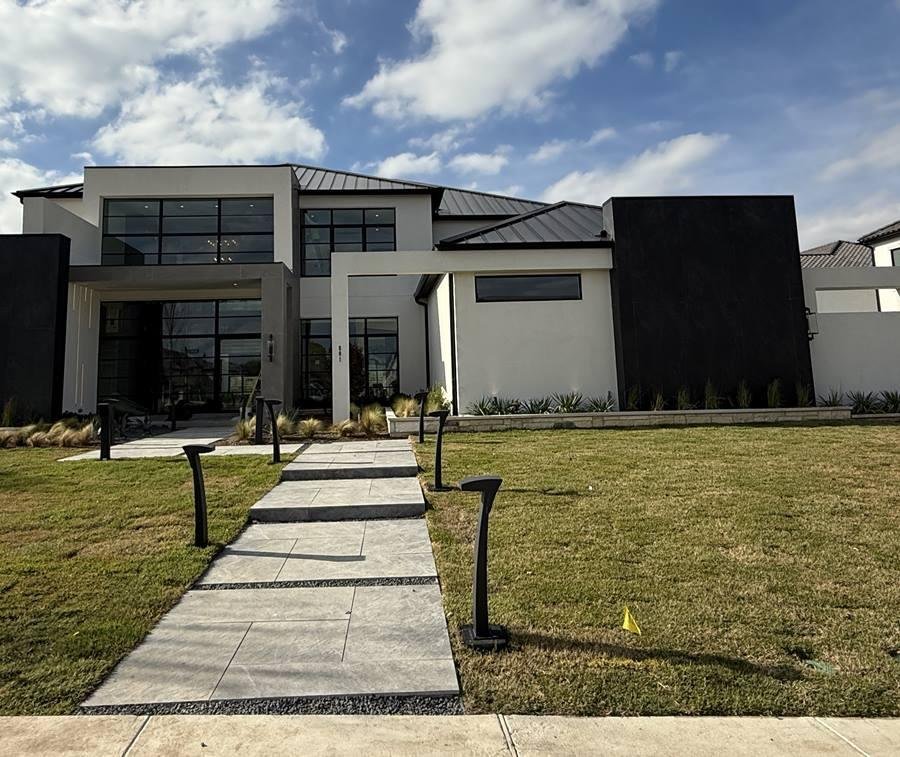
Modern two-story DFW residence, front elevation
Exhibit · front elevation · DFW metro
Justin W. Perry, Certified Residential Appraiser
Perry, Justin W. · Appraiser of record
TX Cert. Residential #1361019
Independence

No stake in the outcome. Fees are never contingent on the value conclusion. The number is the same whether it helps or hurts the tax position, which is exactly why it holds up.

Period data

Sales from the effective date, not today. Comparable sales, market trends, and listing conditions are drawn from the months around the date of death and retained in the work file.

Local competency

Seven counties, appraised daily. Active lender work across the DFW metro means first-hand knowledge of these neighborhoods and how their markets moved during the period in question.

The report answers the question before the IRS or the heirs think to ask it.

Common questions

Sec. 04 · FAQ

What is a date-of-death appraisal?

A date-of-death appraisal is a retrospective appraisal with its effective date set to the day the owner died. It uses comparable sales and market conditions from that date, not from the day of the inspection, and it documents the fair market value the estate, the heirs, and the IRS rely on.

Why does the estate need an appraisal instead of a tax value or an online estimate?

County appraisal district values and automated estimates are not opinions of value by a licensed appraiser, and they are not tied to the date of death. A USPAP-compliant appraisal by a certified appraiser is what the IRS, probate courts, and CPAs expect in the file, and it is what holds up if the value is questioned later.

How long after the date of death can the appraisal be done?

There is no fixed cutoff. Appraisals are routinely completed months or years after the date of death using archived MLS sales and market data from that period. The further back the date, the more the analysis depends on that archived data, all of which is retained in the work file.

What is the alternate valuation date?

Federal estate tax rules allow the executor to elect a valuation date six months after the date of death in some situations. Whether that election applies is a decision for the estate's attorney or CPA. Once the date is set, the appraisal is prepared as of that date, and both dates can be appraised in one engagement when needed.

Who can order an estate appraisal?

The executor or administrator, a trustee, the estate's attorney, or the family's CPA can engage the appraisal directly. No lender is involved. The engagement letter names the client and the intended users so the report can be shared with the people who need it.

Does the property have to be inspected?

An interior and exterior inspection is preferred and produces the strongest report. When the home has already been sold, renovated, or is otherwise inaccessible, the appraisal can be completed from prior records, photographs, and exterior observation, with the limiting conditions stated in the report.
Sec. 05 · Engagement

Request a fee quote for an estate appraisal.

Executors, trustees, attorneys, and CPAs: send the property address, the date of death or other effective date, and who will rely on the report. Letters of engagement, license, and E&O documentation available on request.

Start a quote request →

Family law matter instead? See the divorce appraisal page.

AppraiserJustin, JWP Valuation & Consulting
LicenseTX Certified Residential #1361019
CoverageCollin · Dallas · Denton · Tarrant · Rockwall · Ellis · Grayson